Introduction
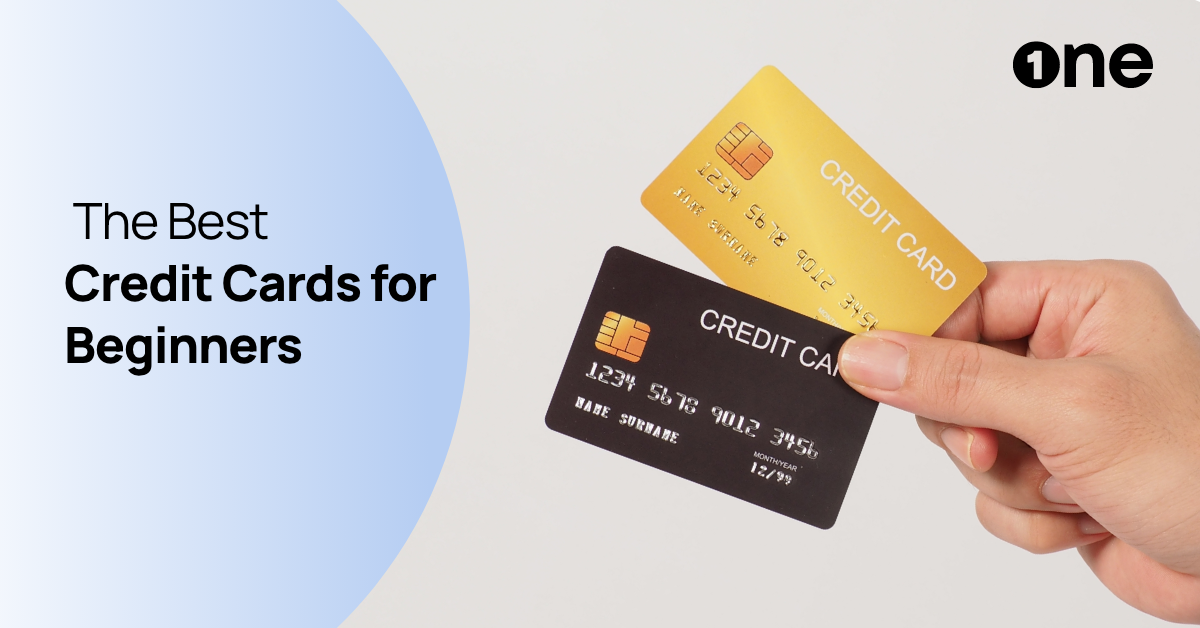
Your first credit card shouldn’t come with unnecessary costs while you’re still learning the ropes. Thankfully, there are several genuinely solid best credit cards for beginners that charge zero annual fee, so you can build credit history without added pressure. Let’s look at what actually matters when picking your first one.
Why No Annual Fee Matters for Beginners
When you’re new to credit, the goal is simply building a healthy history — not chasing rewards or premium perks. A lifetime-free or no-annual-fee card removes the pressure of “using it enough to justify the cost,” letting you focus purely on responsible usage.
For beginners, a no annual fee credit card removes cost pressure entirely, allowing you to focus on building payment history and credit score without worrying about justifying the card’s expense.
What to Look For in a Beginner Card
- Zero or lifetime-free annual fee
- Reasonable interest rate on revolving balances (though ideally you never carry one)
- Basic cashback or reward points on everyday spends
- Easy eligibility criteria for first-time applicants
- Good customer service and app experience
I’ve noticed beginners sometimes get drawn to flashy premium cards with lounge access and high reward rates, without realizing the annual fee often outweighs the benefits at their current spending level.
Categories of No-Fee Beginner Cards
Basic Cashback Cards — Offer a flat percentage cashback on all spends, simple to understand, no complicated reward point conversions.
Fuel and Utility Cards — Good if a large chunk of your monthly spend goes toward fuel or bill payments; often come with waived annual fees on minimum spend.
Secured Credit Cards — Backed by a fixed deposit, ideal if you have no credit history at all or a low score; easier approval, and often genuinely no annual fee.
Building Credit Responsibly With Your First Card
Picture getting your first card and treating the limit as “extra spending money” — that’s the fastest way to build bad habits. Instead, use it for planned expenses you’d pay for anyway, like groceries or fuel, and pay the full bill every month without fail.
[link to related guide on first credit card mistakes to avoid here]
Eligibility for First-Time Applicants
Most beginner-friendly cards require a minimum income of ₹15,000-25,000 monthly for salaried applicants, or an existing bank relationship. Students and those without income proof can often get secured cards against a fixed deposit instead.
Common Waiver Conditions to Watch For
Some cards marketed as “no annual fee” actually mean fee-waived-on-spend, not genuinely free forever. Read the terms carefully — a card requiring ₹50,000 annual spend to waive a ₹500 fee isn’t truly free if you don’t naturally spend that much.
FAQs
Is a no annual fee card as good as a paid premium card? For beginners, yes — the value of premium cards mostly kicks in once you have higher spending patterns that justify the added cost.
Can I upgrade my card later once I build credit history? Yes, most banks allow upgrades to premium cards once you’ve demonstrated 6-12 months of responsible usage.
Do no annual fee cards offer rewards too? Many do, though typically at a lower rate than premium cards — still valuable enough for everyday spending.
Is a secured credit card a good option for absolute beginners? Yes, especially if you have no credit history — it’s often easier to get approved and helps establish your credit profile safely.
What’s the biggest mistake beginners make with their first card? Treating the credit limit as extra income rather than borrowed money that needs repaying in full each month.
Conclusion
Choosing among the best credit cards for beginners doesn’t need to be complicated — prioritize zero annual fee, reasonable terms, and easy eligibility over flashy rewards you likely won’t fully use yet. Use it responsibly for a year or so, and you’ll not only build a solid credit score but also earn the option to upgrade to better cards down the line, on your own terms.